NGX Roars Back: ASI Surges 2.78% In Five Straight Gains To Erase Selloff, Hits 249,804 As Dangote IPO Opens
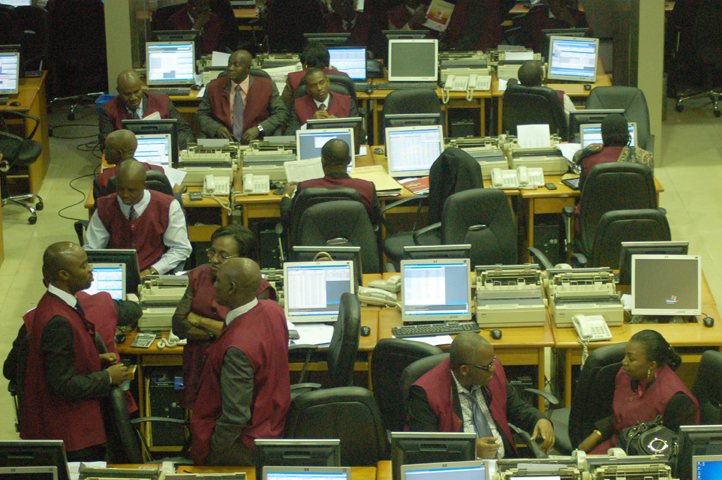
The Nigerian Exchange wiped out last week's losses in a single clean sweep this week, with the All-Share Index closing at 249,804.56 after rising every day from Monday to Friday.
The index gained 278 basis points week-on-week, lifting its year-to-date return to 60.53%. The rally built quietly, up just 10bps on Monday as bidding opened for the Dangote Refinery IPO, before accelerating into a 142bps surge on Friday that pushed the market well above pre-correction levels.
It was a classic reversal trade. The names sold hardest last week were bought hardest this week.
FIRSTHOLDCO led the charge, up 17.65% to close at N160.00, with 8.11% of that gain coming on Friday alone. BUACEMENT swung from floor to ceiling in seven sessions, gaining 6.80% to N297.00, while MTNN jumped 9.73% to N890.00, its 9.20% rally on Friday accounting for most of the day's index move. ARADEL recovered 9.62% to N1,550.00, NESTLE added 3.57% to N2,900.00, and DANGCEM broke a month-long silence with a 1.55% rise to N1,050.00 on Friday.
Banking stocks topped the sector chart, with the NGX Banking Index up 4.43%, though the rally was selective. ZENITHBANK rose 2.47%, WEMABANK 5.26% and FCMB 0.91%, while GTCO, ACCESSCORP, FIDELITYBK and STANBIC ended largely flat. UBA slipped 0.45%. ETI bucked the sector trend, hitting the lower limit on Tuesday and ending down 9.46% at N67.00.
The losing corner was smaller but sharp. TRANSPOWER fell 18.94% to N178.00, PZ shed 11.33% to N73.60 and CADBURY lost 9.32% to N53.00. Brewers were volatile, swinging over 9% intraday, before settling mixed: NB up 0.74%, INTBREW flat, CHAMPION up 9.50%. Consumer goods was the weakest sector at 0.52%. NGXGROUP itself was the most consistent winner, up 21.55% to N179.90 on four consecutive gains.
Turnover eased despite the rally, with 3.17 billion units worth N167.65 billion traded, down from 4.10 billion units worth N171.29 billion the previous week. Offshore flows were the heaviest seen this month, concentrated in ZENITHBANK, STANBIC, HBMNG, NESTLE, GTCO, MTNN and SEPLAT.
For all the strength, the question hanging over the market is the same one that drove this week's narrative: with five straight up days on lighter volumes and an IPO absorbing liquidity in the background, was this true conviction buying, or simply no sellers left?