Dangote's Petrol Hike Raises Verifiability Issue — EBC's David Precious
As Nigeria heads into a new fuel price cycle driven by the escalating 2026 Iran war and volatile Brent crude prices, questions over domestic pricing transparency have taken centre stage.
In this exclusive interview with Financial Edge Odume Festus, David Precious, Senior Market Analyst at EBC Financial Group, dissects the pattern behind the issues and global crude trends, especially what it means for consumers, marketers and investors.
Financial Edge: Let me commend you and your team for this insight, EBC’s analysis says Dangote’s explanation about stored crude cost doesn’t match the timing of the three price increases. Can you walk us through the mismatch?
David Precious: Dangote says the price increases reflect crude purchased weeks earlier, before the decline in global prices. This approach aligns with standard inventory pricing practices. However, the pattern of the changes does not align as cleanly with this explanation.
Between 21, 26, and 29 August, Dangote raised its ex-gantry petrol price three times: first by N20, then by N15, and finally by N65, moving from N1,165 to N1,265 per litre, a total increase of N100 or approximately 8.6% within nine days.
Under a single stored-cost scenario, one would expect a single increase, sized to the cost gap and timed with the entry of the relevant crude into production. Instead, three increases of varying sizes occurred on separate days.
The timing complicates reconciliation. Brent crude declined from around $95 to about $86 during this period, a fall of nearly 10% in five trading days. The two largest increases took place while this decline was ongoing. Crude did not return above $90 until 31 August, two days after the N65 increase took effect.
The subsequent rebound was related to tensions in the Strait of Hormuz, which could only justify a later price movement rather than the one in question. This analysis does not assert that Dangote's explanation is incorrect.
Rather, it shows that external observers lack the data needed to determine which cost drove each increase. For this reason, a published, cargo-by-cargo cost breakdown would resolve the uncertainty more conclusively than argument alone.
Financial Edge: Between 21-29 August, Dangote raised petrol three times by N20, N15, then N65. You noted the increases got larger each time. What does that pattern suggest to you?
David Precious: The initial commentary suggested that the increases grew larger, though this does not precisely reflect the observed pattern. The sequence was N20 on 21 August, N15 on 26 August, and then a substantial N65 on 29 August.
Two modest adjustments followed by a significant jump that accounted for nearly two-thirds of the total N100 increase.This progression reveals more than a uniform rise would. In cases of direct pass-through of purchase costs, price movements typically occur steadily as cargoes are processed.
Instead, two small increments were followed by a larger leap, diverging from the narrative associated with Brent crude, which remained below $90 for over a week during this period.
This does not suggest the N65 figure is erroneous; rather, it highlights a lag, likely because of limitations on which cargoes were acquired at specific times and prices. Identifying those details would clarify the calculation, though current analysis must rely on probable assumptions. The absence of a published cost breakdown maintains this gap.
Financial Edge: Brent crude fell nearly 10% from $95 to $86 during that same window. The two largest increases came while crude was still falling. How do you reconcile that with a cost-pass-through model?
David Precious: Pricing stored crude at acquisition cost rather than current spot price remains standard practice for refiners. However, the sequence of price changes does not align with this principle: three increases occurred over nine days, with the two largest occurring as Brent crude declined from about $95 to $86.
The subsequent rebound does not account for a prior increase. Reconciling this requires knowing which cargo drove the N65 increase, its purchase date, and its price. These details are not publicly disclosed.
The model, therefore, remains neither disproven nor verifiable in this context; only transparency can resolve the uncertainty. An apt analogy is an invoice for a shipment purchased the previous month: such an invoice should not undergo three revisions within nine days without new justification, nor should its largest increase coincide with the steepest market price drop.
Financial Edge: Dangote says prices reflect crude bought weeks earlier when Brent was above $90. In normal refinery operations, what’s the expected lag between buying crude and reflecting that cost at the gantry?
David Precious: Dangote obtains crude from two primary sources: domestic Nigerian crude under the naira-for-crude arrangement and imported cargoes from Angola, Algeria, and the United States, paid in dollars.
The domestic supply has consistently fallen short of commitments, resulting in a substantial portion of the refinery's feedstock being imported crude, which is subject to a genuine multi-week lag.
For imported crude, comparable West African and transatlantic shipping routes typically require two to three weeks in transit, not including negotiation, contracting time before loading, and the period the cargo remains in storage before being processed and priced at the gantry.
Nigeria's previous fuel-pricing regulator cited a figure of about 30 days for a different route, Northwest Europe to West Africa, but this does not precisely reflect Dangote's actual import origins.
The two-to-three-week estimate, based on Dangote's sourcing patterns, provides a more accurate reference for this context. The term weeks is not used as a vague estimate in relation to the imported proportion of the supply mix; it accurately describes the supply chain.
This distinction also clarifies why the claim of being insulated from global price swings does not fully hold, as a significant portion of Dangote's crude is imported due to shortfalls from the naira-for-crude arrangement.
Financial Edge: On 27 August, Dangote was pricing about N22 below import-parity. Two days later at N1,265, it was about N43 above. Without a live benchmark, how can marketers or regulators tell if an increase is justified by cost?
David Precious: The shift from N22 below to N43 above import-parity does not constitute new evidence by itself; it is the N65 increase viewed relative to a fixed reference point.
On 27 August, MEMAN's bulletin listed Dangote's gantry price at N1,200 and the estimated import-parity level at N1,222.32, placing the price about N22 below parity.
Two days later, the new N1,265 price stands approximately N43 above the same reference. This calculation represents the same N65 increase expressed from a different perspective. Such a comparison does not independently confirm whether the adjustment was justified; it merely reframes the same numerical change.
Currently, marketers and regulators lack the means to verify in real time whether a price increase reflects actual costs or exceeds them. The only available reference is a periodic bulletin, which provides a snapshot from several days before the price movement. Information regarding whether import parity shifted during those two days remains unavailable outside the organisation.
Publishing a cost breakdown for each adjustment, including cargo, purchase date, price, and discharge date, would enable marketers, regulators, and future shareholders to evaluate each change using current data rather than outdated references.
Financial Edge: NNPC raised its pump price within days of each Dangote increase. Does this mean we now have one dominant price-setter rather than two competing suppliers?
David Precious: NNPC's Abuja and Lagos prices changed within days of each Dangote increase. This sequence is a factual observation. Whether this pattern reflects a single dominant price-setter rather than two competing suppliers is a broader issue and should be separated from the immediate facts.
Examining supply separately from pricing, NMDPRA's monthly data recorded Dangote's share of Nigeria's domestic petrol supply at about 72%, rising to around 88% The May report attributed the entire domestically refined volume to Dangote, with no output from a second refiner.
Although this share has since declined due to reduced refinery output and increased imports, the fundamental market structure remains unchanged. No rival refiner operates at a comparable scale.
NNPC and independent marketers are primarily importing, or, according to their trade association, sourcing product from Dangote.When NNPC's pump price closely follows Dangote's within a short time frame, this is consistent with a market in which the second supplier has limited independent cost basis for pricing.
This does not imply coordination, and the analysis does not make that claim. Some marketers and members of the public have described the situation as a "monopoly". However, a competition regulator makes that determination. The key point is that as independent pricing power diminishes elsewhere, verification increasingly focuses on Dangote, since there is no alternative price for comparison.
Financial Edge: IPMAN said retailers had "no choice but to raise pump prices." What does that tell us about competition and price transmission in Nigeria’s downstream sector?
David Precious: The IPMAN statement may be taken largely at face value, but it is important to consider the nature of such claims. As a representative body for independent retailers, IPMAN's assertion of having "no choice" also defends its members and redirects public scrutiny upstream.
This does not necessarily render the claim inaccurate, yet it is not a neutral interpretation of market dynamics. Rapid, near-complete pass-through, as observed within days of each Dangote adjustment, aligns with expectations for a genuinely competitive retail segment.
Retail margins on petrol in Nigeria are so narrow that marketers have frequently reported genuine losses when wholesale prices shift against inventory already in stock.
Earlier in the year, independent marketers indicated financial losses on unsold inventory when both NNPC and Dangote reduced prices within a short interval. A retailer without sufficient margin must pass on cost changes quickly or absorb the loss.
These conditions suggest that the retail tier is competitive.However, where this competition occurs in the supply chain is crucial. While retail competition keeps margins narrow and forces swift price transmission, it does not put downward pressure on the wholesale price, which a single refiner set upstream when it supplied up to 88% of the domestic market.
Competition can confirm that marketers are not inflating their own share, but it cannot establish whether the underlying input cost is justified. Rapid price transmission ensures that charges set by Dangote reach the pump promptly and with minimal dilution, but this alone does not validate the original wholesale figure.
Financial Edge: NMDPRA listed crude sourcing, logistics, and single-source refining as drivers of volatility. Which of these do you think had the biggest role in the August increases?
David Precious: Selecting a single driver would not be appropriate in the absence of underlying data, which is a central point of this analysis. It would mirror the same practice under scrutiny.
The three factors are also not of the same nature. Crude sourcing and logistics or transport costs are valid candidate cost components; either could explain a portion of a specific increase, though only Dangote's internal records would reveal which factor contributed and to what extent.
Single-source domestic refining" is distinct, as it is not a driver of an individual increase but rather the reason independent verification is not possible. With no second domestic refiner's price available for comparison, the market lacks an external benchmark.
A review of publicly reported operational issues within the relevant period, such as shipping delays or supply disruptions, yielded no evidence pointing to a particular cause. The absence of corroborating signals from external sources supports the case for greater disclosure.
Given the current state of evidence, it is not possible to determine which factor played the largest role. This uncertainty underscores the value of a published, per-adjustment cost breakdown, which would provide a more definitive answer than speculative assessment.
Financial Edge: For two years the promise has been that naira-for-crude and local refining would protect Nigerians from global price swings. Does this episode undermine that?
David Precious: Two distinct claims are often conflated in this discussion, yet the evidence for each differs. The first concerns volume: whether naira-for-crude has delivered as intended.
NNPC committed to approximately 350,000 barrels per day, while Dangote leadership reported to Reuters that actual deliveries have often been significantly lower, sometimes closer to 120,000 barrels per day, with supply reportedly suspended entirely for a period in early 2025. Dangote also temporarily adopted dollar pricing for local sales in July, attributing this shift to the supply shortfall.
On the supply front, the available record already shows clear underperformance, as Dangote itself acknowledges.The second claim is more specific and is the focus of this release: even when crude supply is maintained, does the resulting pump price reliably track input costs in line with the promise of insulation from global price swings?
In August, the alignment was not clear. One episode alone does not prove the two-year promise has failed, as nine days of data cannot bear such weight. However, the pattern suggests that the promise has not yet been fully realised, both in terms of supply and, more recently, pricing.
Whether this constitutes policy failure is a matter for policymakers and the public to determine, a task best undertaken with full disclosure rather than by evaluating isolated incidents.
Financial Edge: You flagged that this matters for investors ahead of Dangote’s reported $40 billion listing. What specific disclosures would give investors' confidence in the pricing model?
David Precious: Timing is significant in this context. The SEC approved the offer on 6 September, and the registration of approximately 120 billion ordinary shares implies a valuation closer to $47 billion, exceeding the nearly $40 billion figure cited in the original release, which referred to a July private placement.
This updates the previous valuation rather than contradicting it. The order book opened on 14 September, so the focus is on the information available to investors at subscription, not on potential future disclosures.The term "disclosure" refers to two distinct elements. Once available to the public, the prospectus will provide audited figures for revenue, margins, and debt for the first time.
These are important and merit careful review, particularly regarding crack-spread assumptions and leverage. However, this information is retrospective. It does not address how future pricing decisions will be made, which is the central concern in this case.
Standard IPO risk factors, such as oil price exposure, currency risk and market concentration, are included in all energy sector listings, but none require a company to disclose the rationale for specific price adjustments after the fact.
More concretely, the following would provide greater clarity: publication of a cost breakdown for each price adjustment, detailing the cargo, purchase date, price and discharge date; regular disclosure of the crude supply mix, distinguishing between naira-denominated domestic supply and dollar-denominated imports, as this ratio determines both foreign exchange exposure and pricing lag; an independently verifiable reference price updated more frequently than periodic bulletins, given the absence of a live import-parity benchmark; and confirmation that crude and logistics purchases from affiliated Dangote Group entities are conducted at arm's length, which should be considered standard practice for a business of this scale rather than an exceptional requirement.
Financial Edge: What kind of cost breakdown per adjustment would resolve the ambiguity? Cargo date, purchase price, discharge date is that standard at other major refineries?
David Precious: A regularly published pricing formula, rather than a cargo-by-cargo ledger, would address the ambiguity. Nigeria applied such a model for more than a decade prior to deregulation.
The former PPPRA pricing template presented a comprehensive breakdown: landing cost calculated from freight and insurance referenced to Platts, an independent benchmark, not the seller's own assessment, along with financing, storage and port charges, and a distribution margin, all updated monthly. PPPRA was dissolved in 2021 following the implementation of the Petroleum Industry Act, which incorporated it into NMDPRA.
The same legislation formalised deregulation, making this template a historical example rather than a current requirement.The precise price paid for an individual shipment is not typically disclosed by any major refiner, whether public or private, as such detail is commercially sensitive.
What is required is a consistent formula referenced to an independent benchmark, which provides external parties with a means to verify claims.This is not an argument for the reintroduction of price controls; the PPPRA template previously supported a subsidised price.
It remains possible to set a market-driven price while also publishing the underlying pricing formula. Transparency regarding methodology does not necessitate control over the outcome.
Financial Edge: Dangote also raised diesel by N100 on 4 September. Is the same timing issue present there, or is diesel priced on different fundamentals?
David Precious: The diesel pricing pattern contrasts with that of petrol. Over the period, diesel prices adjusted three times rather than changing once. Dangote increased the diesel price from N1,570 to N1,670 around 20 August, referencing crude oil valued near $94, just before Brent fell to $86 by 26 August.
Diesel prices remained unchanged during this decline and held steady while petrol prices rose. When Brent rebounded above $90 on 31 August and continued to rise toward $100, diesel prices increased again, first to N1,750 around 1 September, then to N1,850 on 4 September, as referenced in the release.
Placing these changes side by side reveals distinct trends. The two largest petrol price increases occurred while crude prices were falling. In contrast, the diesel price increases, both mentioned and unmentioned, coincided with periods when crude prices were elevated or rising, while diesel prices remained stable during the precise window in which crude declined.
This pattern aligns with genuine cost pass-through, where price movements reflect the direction of input costs rather than opposing them. While this does not confirm the scale of the diesel price increases, because Dangote's specific diesel cargo costs remain undisclosed, the same call for transparency applies.
Diesel pricing does not present the same immediate concerns as petrol pricing. If anything, this comparison highlights the petrol issue more sharply by demonstrating that Dangote's pricing can follow crude oil trends, indicating that the unusual petrol pricing pattern observed in August is not a consistent feature of the pricing approach.
Financial Edge: Brent climbed back above $90 on 31 August after the last hike. Should consumers expect another increase, and how will we know if it’s due to crude cost or geopolitical risk?
David Precious: As of 11 September 2026, Brent is trading around $105 to $107 a barrel, roughly 19% higher than a month earlier, not just back above $90. The driver is an active, escalating conflict, not a passing scare: the 2026 Iran war, underway since late February, has widened through the summer into direct US-Iran strikes and attacks on shipping near the Strait of Hormuz, and this week a fresh Saudi-Houthi escalation pushed Brent to its highest level since May.
If Dangote's own stored-cost, weeks-later logic holds, a move this size in the input should show up as a further price increase in the coming weeks, and if it does, it would look different from August: this time the size and direction of the crude move would genuinely support an increase, rather than contradicting it.Crude cost and geopolitical risk aren't two different explanations here; the risk is what's driving the cost.
The real test is whether the size and timing of any move matches the size and timing of this crude move, using the same public data we've used throughout: Brent's price history and the date a new price takes effect.
For anyone trading rather than just reading about this, Brent's direction and persistence matter, not any single day's print. A spike that fades in a week reads very differently from one that holds.
Financial Edge: If you had 2 minutes with Dangote’s leadership before the IPO, what is the one question about pricing transparency you would press them on?
David Precious: A general assurance of transparency is not readily verifiable, as it provides no measurable benchmark for investors. Such statements lack specificity and therefore offer limited value in assessing future conduct.
A more effective question would focus on a specific commitment: whether the company will publish, in writing, a regular, formula-based breakdown of the ex-gantry price. This breakdown should detail cost categories referenced to an independent benchmark and be updated on a fixed schedule, commencing with the listing.
The company has previously advocated for increased transparency regarding import volumes from other market participants, citing planning uncertainty as a consequence of limited information.
The same principle applies to its own pricing approach. A clear commitment to this mechanism would provide investors with concrete information during the subscription period, while the absence of such a commitment would allow investors to make an informed judgment.
Financial Edge: From an investor standpoint, what’s the biggest risk if this pricing ambiguity isn’t addressed before the listing?
David Precious: From an investment perspective, the main risk is verifiability rather than the ultimate valuation, which is a separate consideration. Independent reporting on the IPO has indicated that Dangote's recent earnings have been enhanced by disruptions caused by the conflict in Iran, alongside generally stronger refining margins across the industry.
The same reporting references Rob Thummel, a senior portfolio manager at Tortoise Capital Management, who notes that Dangote does not disclose its margins and highlights he risk associated with dependence on a single crude supplier.
Additionally, Gulf Times has observed that some investors and analysts consider the reported valuation relatively high compared to other standalone listed refiners. These are external assessments; no endorsement or opposition is expressed regarding the stated valuation range.
The salient concern remains the persistent gap already identified, now viewed at company scale. If margins are not independently verifiable at the consumer level, the same challenge applies to the figures underpinning a public listing.
Reporters and investors currently assess valuations without such verification, underscoring the importance of disclosure before subscription rather than as a retrospective consideration. To contextualise the potential impact, Dangote's domestic petrol supply is approximately 40 million litres per day.
If even a portion of a single price increase, such as the N65 adjustment in August, represented margin rather than direct cost, this would constitute a significant and recurring contribution to the earnings base subject to valuation.
This example illustrates scale, not the composition of the N65 figure, which remains unverifiable outside the company. The fundamental risk lies not in any specific number, but in the absence of external verification.
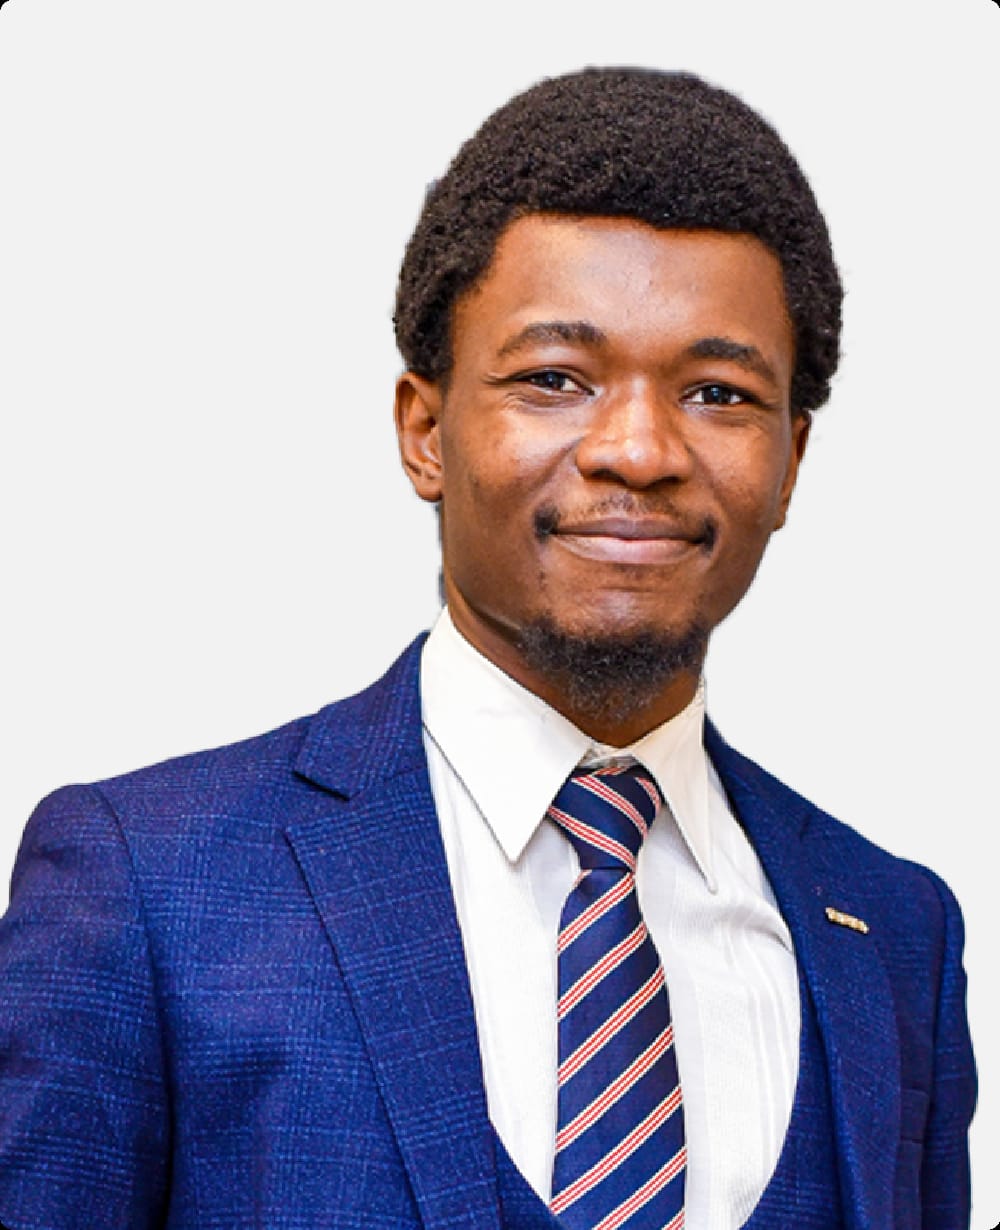
Photo Caption: David Precious, Senior Market Analyst at EBC Financial Group